Convertible Performance Across Market Environments: Implications for Insurance Portfolios
By David Tyson, Ph.D., CFA, Managing Director and Portfolio Manager; Andrew Willard, Assistant Vice President, Portfolio Management
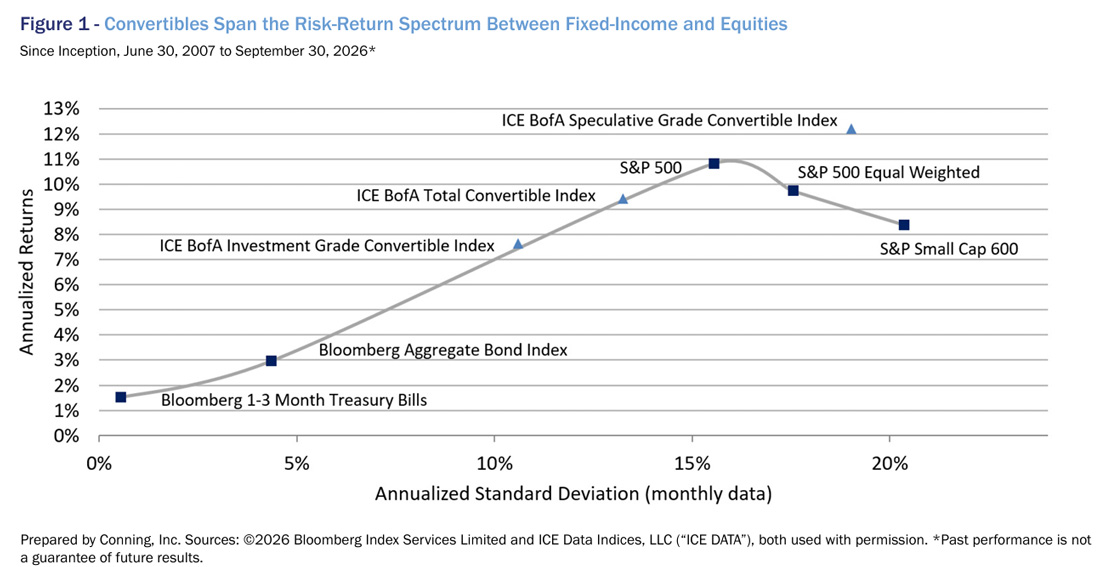
Convertibles occupy a distinctive position between equities and fixed income. Their hybrid structure is designed to offer equity-market participation while retaining a measure of downside protection through the security’s fixed-income value.
For insurers, higher-quality convertibles may also offer capital-efficiency benefits relative to direct equity allocations. These characteristics can be particularly relevant when traditional portfolio exposures are challenged by changing market conditions. Convertibles may provide equity participation when markets are rising, potentially offer less interest-rate sensitivity than longer duration bonds when rates increase, and provide a differentiated source of resilience when stocks and bonds decline together.
This Viewpoint examines how convertibles have performed across three distinct market environments and the potential implications for insurance portfolios.
Three environments where convertibles could be helpful:
- Equity market declines: Maintain equity exposure while retaining downside protection from the fixed-income value.
- Rising interest rates: Participate in equity-market gains while potentially carrying less interest-rate sensitivity than longer-duration bonds.
- Declining stock and bond markets: Provide a differentiated return profile when traditional asset classes decline together.
Risks of Investing in Convertible Bonds
Equity market declines which reduces the value of convertibles’ equity conversion features.
A high level of corporate defaults or a sharp widening in corporate bond spreads which reduces the value of convertibles’ fixed income floors.
Low supply of issues due to prolonged low interest rates and strong demand for investment grade corporate and high yield debt.
Disclosure
©2026 Conning, Inc. Conning, Inc., Goodwin Capital Advisers, Inc., Conning Investment Products, Inc., a FINRA-registered broker-dealer, Conning Asset Management Limited, and Conning Asia Pacific Limited (collectively “Conning”) and Octagon Credit Investors, LLC, Global Evolution Holding ApS and its subsidiaries, MGG Investment Group LP and certain of its affiliates, and Pearlmark Real Estate, L.L.C. and its subsidiaries (collectively “Affiliates” and together with Conning, “Conning & Affiliates”) are all direct or indirect subsidiaries of Conning Holdings Limited which is one of the family of companies whose controlling shareholder is Generali Investments Holding S.p.A. (“GIH”) a company headquartered in Italy. Assicurazioni Generali S.p.A. is the ultimate controlling parent of all GIH subsidiaries. Conning & Affiliates have investment centers in Asia, Europe and North America. This document and the software described within are copyrighted with all rights reserved. No part of this document may be distributed, reproduced, transcribed, transmitted, stored in an electronic retrieval system, or translated into any language in any form by any means without the prior written permission of Conning & Affiliates. Conning & Affiliates do not make any warranties, express or implied, in this document. In no event shall any Conning & Affiliates company be liable for damages of any kind arising out of the use of this document or the information contained within it. This document is not intended to be complete, and we do not guarantee its accuracy. Any opinion expressed in this document is subject to change at any time without notice.
This document is for informational purposes only and should not be interpreted as an offer to sell, or a solicitation or recommendation of an offer to buy any security, product or service, or retain Conning & Affiliates for investment advisory services. The information in this document is not intended to be nor should it be used as investment advice.
Copyright 1990-2026 Conning, Inc. All rights reserved.
Additional Source Information
ICE Data Indices, LLC (“ICE DATA”), is used with permission. ICE DATA, ITS AFFILIATES AND THEIR RESPECTIVE THIRD PARTY SUPPLIERS DISCLAIM ANY AND ALL WARRANTIES AND REPRESENTATIONS, EXPRESS AND/OR IMPLIED, INCLUDING ANY WARRANTIES OF MERCHANTABILITY OR FITNESS FOR A PARTICULAR PURPOSE OR USE, INCLUDING THE INDICES, INDEX DATA AND ANY DATA INCLUDED IN, RELATED TO, OR DERIVED THEREFROM. NEITHER ICE DATA, ITS AFFILIATES NOR THEIR RESPECTIVE THIRD PARTY SUPPLIERS SHALL BE SUBJECT TO ANY DAMAGES OR LIABILITY WITH RESPECT TO THE ADEQUACY, ACCURACY, TIMELINESS OR COMPLETENESS OF THE INDICES OR THE INDEX DATA OR ANY COMPONENT THEREOF, AND THE INDICES AND INDEX DATA AND ALL COMPONENTS THEREOF ARE PROVIDED ON AN “AS IS” BASIS AND YOUR USE IS AT YOUR OWN RISK. ICE DATA, ITS AFFILIATES AND THEIR RESPECTIVE THIRD PARTY SUPPLIERS DO NOT SPONSOR, ENDORSE, OR RECOMMEND CONNING, OR ANY OF ITS PRODUCTS OR SERVICES.
Bloomberg Index Services Limited. Used with permission. Bloomberg is a trademark of Bloomberg Finance L.P. and its affiliates (collectively “Bloomberg”). Bloomberg does not approve this material, guarantee the accuracy of any information herein, or make any warranty as to the results to be obtained therefrom, and shall not have any liability for injury or damages arising in connection therewith.
COD00002950